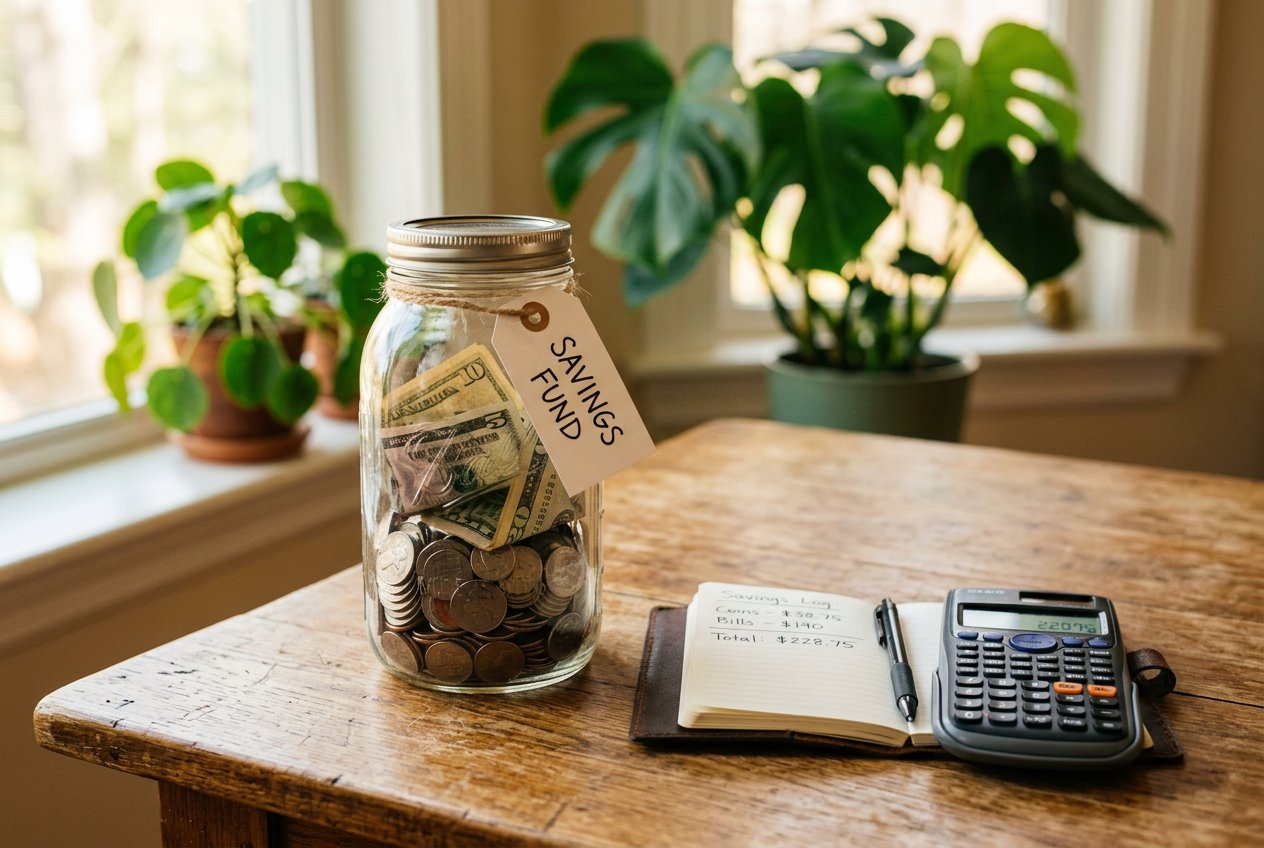
Almost every financial plan we write starts in the same place, and it is not the investment portfolio. It is a boring, unglamorous cash reserve that sits in a separate account and does nothing until something goes wrong. Clients who have one make better decisions for the rest of their lives, because they stop being forced to borrow at the worst possible moment.
The problem is that "save three to six months of expenses" sounds less like advice and more like a rebuke, especially when the month is already tight. The trick is to stop treating an emergency fund as a lump sum you must find somewhere and start treating it as a system you install. Systems get built in a single afternoon. Targets tend to wait until next year.
Start with the right number, not the perfect number
Your first goal is not three months of income. It is one month of essential expenses. Essentials means housing, utilities, food, transport, insurance, minimum debt payments and childcare. It does not include streaming subscriptions, dining out or the gym. Most households discover this number is meaningfully smaller than they feared, and knowing it precisely is what makes the goal feel achievable.
Write that single figure down. If it turns out to be $3,400, then your first milestone is $3,400, and that is the only number that matters for the next several months. Once you reach it, the second milestone is three months, then six if your income is variable or you support a family on one salary. Layered targets keep motivation intact in a way that a distant six-month goal never does.
Calculate your essentials in ten minutes
Open the last three months of bank statements and highlight only the payments you could not cancel without serious consequences. Average the total, and that is your monthly essentials figure. Everything else is discretionary and belongs in a different conversation.
Automate the transfer before you see the money
The single highest-impact change most clients make is moving the transfer date to the same day their salary lands, then deleting the debit card from their wallet app. Money that never appears in the spending account does not get spent. It sounds trivial, and it outperforms willpower by a wide margin in every budget study we have seen.
Set the amount at a level you will not cancel in week three. Fifty dollars a week beats two hundred dollars once and then nothing for four months. If your income is irregular, automate a small fixed amount and add a second transfer whenever a good month arrives — many people use a rule like "half of any windfall goes straight to the reserve".
An emergency fund is not an investment. It is insurance you own instead of rent — and the return shows up as the decisions you no longer have to make under pressure.
Where to keep it matters more than you think
The reserve needs three properties: it must be safe, it must be available within a day, and it must be slightly annoying to reach. A high-yield savings account at a separate institution satisfies all three. A checking account attached to your daily spending fails the third test, which is why so many "savings" balances quietly disappear.
Keep the emergency fund out of the stock market. It is tempting to chase a better return, but the whole point is that the money is there on the day the market is down and the transmission has failed. Certificates of deposit can work for a portion once the fund is fully built, provided the terms are short and you stagger the maturity dates.
Use it, then refill it — without guilt
A reserve that you are afraid to touch is not a reserve; it is a museum exhibit. When a genuine emergency arrives, spend the money, resolve the problem and then restart the automated transfer. The only failure mode is treating a withdrawal as permission to abandon the system altogether.
It also helps to write down, in advance, what counts as an emergency. Job loss, medical bills, a necessary home or vehicle repair and travel for a family emergency clearly qualify. A holiday sale, a wedding gift or a new phone usually do not — those belong in a separate sinking fund with its own monthly contribution.
Finally, review the fund once a year. If rent rose, a child arrived or your income changed, the target changes too. Clients who revisit the number annually tend to stay funded for decades, while those who set it once and forget it drift back toward zero within a few years. The system, not the amount, is what keeps you resilient.
Want this mapped to your own numbers?
Book a free 30-minute consultation. We will review your situation and give you three concrete next steps — no obligation, no sales script.